What is the scope and industry significance of the Pipe Alignment Clamp Market?
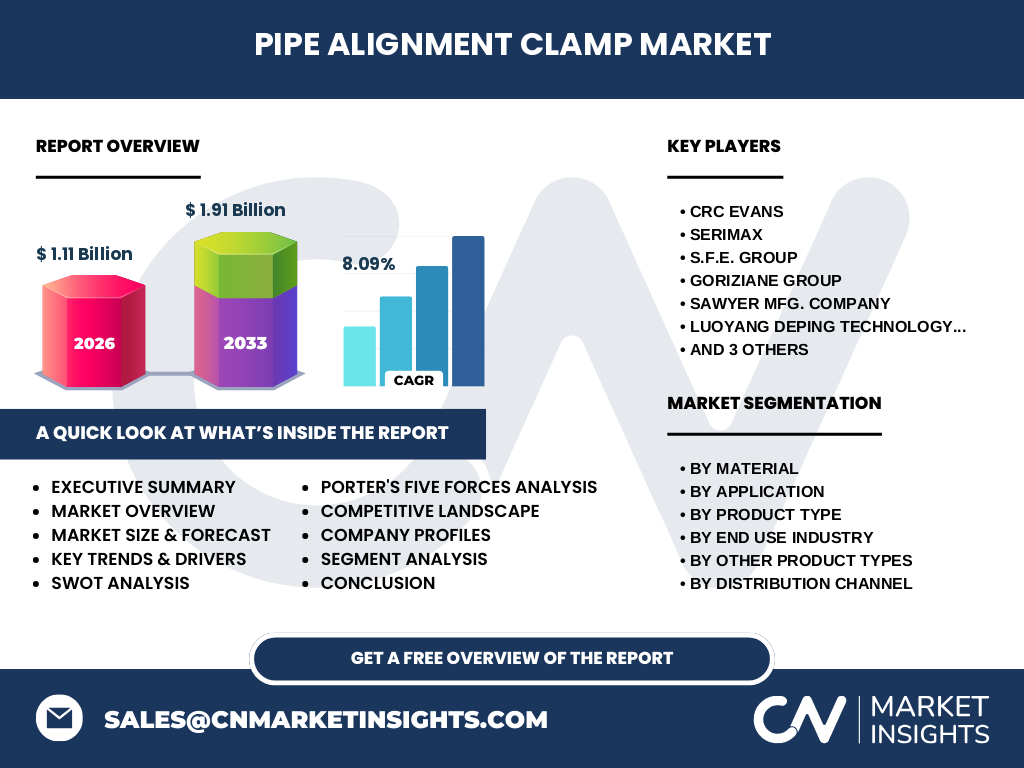
Our analysis indicates that the Pipe Alignment Clamp Market encompasses specialized mechanical, hydraulic, and pneumatic tooling vital for high-integrity welding across energy and infrastructure sectors. Valued at 1.11 Billion in 2026, these precision instruments prevent angular misalignment and high-low defects during critical pipeline installation and tank fabrication phases.
Structural Growth Drivers and Market Restraints
The market is propelled by surging cross-border energy transmission projects and strict compliance standards enforced by bodies like ASME and ISO. However, high initial capital expenditures for advanced internal pneumatic systems and supply chain bottlenecks for alloy steels represent persistent operational headwinds for contractors.
Emerging Industry Trends in Pipe Alignment Clamp Technology
A definitive shift toward automated internal hydraulic alignment systems is transforming field productivity. Contractors increasingly demand quick-release snap-fit clamps and specialized copper backing shoes to minimize weld distortion in high-alloy line pipe applications, directly reducing costly project rework rates.
COVID-19 Impact Analysis and Post-Pandemic Recovery
The pandemic severely disrupted global supply chains, halting major oil and gas pipeline construction. Recovery has been robustly steered by stimulus-backed municipal water infrastructure spending, allowing leading manufacturers to clear backlogs and accelerate automation integration across their production lines.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains moderate to high, featuring heavyweights like CRC Evans, Serimax, and S.F.E. Group dominating international projects. Competitors increasingly differentiate through proprietary quick-release mechanisms and robust global distribution networks that ensure rapid on-site parts replacement.
Executive Summary of the Pipe Alignment Clamp Market
Driven by robust infrastructure investments, the Pipe Alignment Clamp Market industry trends point toward a robust valuation of 1.91 Billion by 2033. Operating at a compound annual growth rate of 8.09% from 2027 to 2033, the sector rewards innovation in heavy-duty hydraulic and magnetic configurations.
Market Forecast and Long-Term Valuation Trajectory
Based on our econometric modeling, the market will expand from its 2026 baseline of 1.11 Billion to reach 1.91 Billion by 2033. This consistent 8.09% CAGR underscores sustained long-term demand across offshore shipbuilding and subterranean water transmission networks.
Comprehensive Segmentation Analysis
The market segments by material (steel, aluminum, plastic), product type (manual, hydraulic, pneumatic), application (welding, fit-up, repair), and end-use (oil & gas, construction, chemical). Steel variants retain dominant revenue shares due to extreme durability demands in heavy industrial settings.
Geographic Distribution and Regional Market Performance
North America and APAC represent the primary revenue engines, fueled by extensive shale pipeline maintenance and rapid urbanization. Logistical hubs around major maritime ports facilitate seamless cross-border distribution of specialized heavy-duty hydraulic clamps for mega-projects.
In-Depth Regional Review of High-Growth Zones
APAC exhibits the fastest regional growth rate, driven by expansive chemical plant expansions and offshore maritime construction in Southeast Asia. Meanwhile, strict environmental mandates in Europe accelerate the adoption of precision internal alignment systems to eliminate fugitive emissions.
Company Profiles and Strategic Positioning
Industry leaders such as Goriziane Group, Sawyer Mfg. Company, and Luoyang Deping Technology leverage targeted R&D to capture regional energy contracts. Meanwhile, firms like H&M Pipe Beveling Machine Co. and Core Pipeline Equipment focus on niche manual and magnetic clamp portfolios.
Porter's Five Forces Analysis of Competitive Intensity
Bargaining power of buyers is moderate, mitigated by the critical need for certified weld quality. Threat of substitutes remains low given strict regulatory mandates for pipeline integrity, though rivalry among established manufacturers like Shree Shakti Engineering keeps margin pressure high.
SWOT Analysis of the Global Industry
Core strengths include robust mechanical durability and high proprietary patent portfolios. Weaknesses center on high alloy steel price volatility. Opportunities lie in emerging renewable hydrogen pipelines, while threats involve geopolitical trade tariffs impacting raw material logistics.
Value Chain Analysis from Raw Materials to End-Users
Value creation flows from high-grade raw material extraction (aluminum and structural steel) through precision CNC machining and assembly. Distributors and direct sales channels then deliver these certified tools to EPC contractors operating in remote oilfields and shipyards.
Strategic Investment Insights and High-Potential Areas
Investors should target manufacturers specializing in lightweight aluminum and magnetic clamping solutions tailored for modular fabrication yards. Companies integrating IoT-enabled clamping feedback mechanisms present exceptional upside potential as automation sweeps heavy industrial fabrication.
Conclusion and Definitive Industry Takeaways
The Pipe Alignment Clamp Market analysis confirms a thriving sector poised to reach 1.91 Billion by 2033. Success relies on technological adaptation, particularly embracing hydraulic and pneumatic innovations that reduce project downtime and satisfy stringent global safety codes.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining international trade registry data, primary stakeholder interviews with chief welding engineers, and secondary macroeconomic indicators from industrial manufacturing associations to ensure absolute market intelligence accuracy.
Scope of the Report and Coverage Parameters
This report covers global revenue performance for the Pipe Alignment Clamp Market from 2026 to 2033. Limitations exclude unregulated artisanal fabrication tools, focusing exclusively on enterprise-grade commercial clamping assets utilized in regulated industrial and energy applications.
Recent Corporate Developments and Strategic Strategic Moves
Recent industry momentum features major players expanding their manufacturing footprints through strategic acquisitions and localized distribution partnerships. Companies are aggressively launching IoT-integrated pneumatic systems to capture market share in high-precision offshore fabrication hubs.